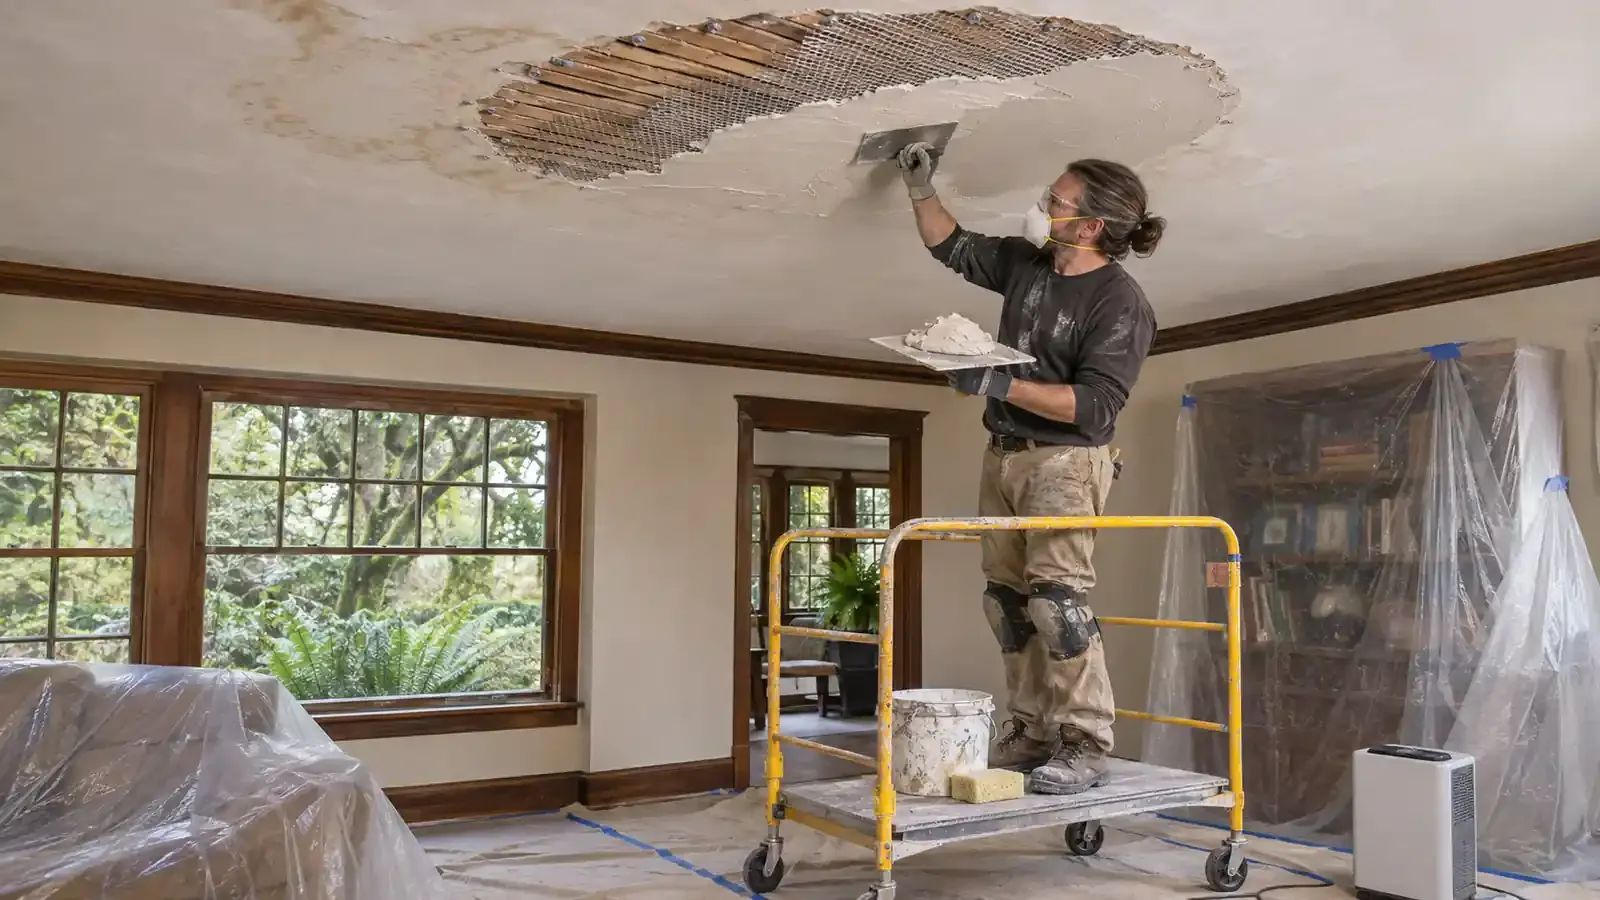


A frozen pipe claim can look straightforward: the building lost heat, a pipe split, and water damaged the property. Insurance coverage is less automatic. The answer depends on whether the policy matched the building’s actual use, what its freezing exclusion required, why the heat failed, and which losses the owner or tenant is claiming.
So, does home insurance cover frozen pipes when a vacant or rental property loses heat? Often, a property policy can cover sudden water damage caused by a frozen pipe.
Coverage may be limited or denied, however, when the insured did not use the care required by the policy to maintain heat or shut off and drain the plumbing. Vacancy or a change to rental use can create additional coverage questions. The actual policy, endorsements, timeline, and facts control the claim.
The Claim Has Four Gates, Not One Yes-or-No Rule
The most useful way to assess a frozen-pipe loss is to work through four separate questions. A favorable answer at one gate does not settle the others.
1. Did the Policy Match the Property’s Actual Use?
A standard homeowners policy is generally designed for an owner-occupied residence. A long-term rental commonly needs a landlord or dwelling policy, while a genuinely vacant home may need a vacancy endorsement or specialty policy.
If the insurer was told the home was owner-occupied but it had become a rental or sat empty for an extended period, the occupancy mismatch can create a coverage problem before the frozen pipe is even considered.
There is no universal number of days after which every property becomes “vacant.” Definitions and time periods differ, and policies may distinguish a furnished but temporarily unoccupied home from a building without occupants or enough contents for normal living. Check the definitions, conditions, and endorsements in the policy rather than relying on a 30-day or 60-day rule found online.
2. What Does the Freezing Provision Require?
Many property policies condition freezing coverage on whether the insured used reasonable care to:
- Maintain heat in the building; or
- Shut off the water supply and drain the plumbing systems and appliances.
The exact wording matters. Some provisions use alternatives, while others add conditions for sprinkler systems or particular equipment. The Oregon Division of Financial Regulation specifically cautions that frozen-plumbing damage in an empty house may not be covered unless heat is maintained or the pipes are drained.
3. Why Did the Property Lose Heat?
Turning the thermostat off before leaving is materially different from a documented utility outage, a sudden furnace failure, or a tenant changing the setting contrary to written instructions. Even so, none of those facts guarantees an outcome.
The insurer may investigate what precautions were reasonable, who controlled the heat, how long the condition lasted, whether anyone monitored the property, and what happened after an alert or warning.
A power failure does not automatically make the resulting water damage covered. It can be important evidence that the insured did not intentionally leave the building without heat, especially when paired with timely action, maintenance records, and proof that the property was monitored.
4. Which Part of the Loss Is Being Claimed?
Coverage is not necessarily all or nothing. A policy may treat these expenses differently:
- Opening a wall to reach the failed plumbing;
- Repairing or replacing the split pipe itself;
- Drying and repairing wet walls, ceilings, insulation, flooring, or cabinets;
- Replacing an owner’s appliances or furnishings;
- Paying fair rental value after a covered loss makes a unit unfit to rent; and
- Covering a tenant’s belongings or additional living expenses under the tenant’s own renters policy.
Oregon’s insurance regulator notes that homeowners coverage generally addresses resulting damage from an accidental frozen-pipe discharge, while repair of the pipe itself is usually the homeowner’s responsibility. Policy language can change that division.
Vacancy and Rental Use Create Different Coverage Questions
An empty property is not automatically a rental, and a rental is not automatically vacant. Identifying the actual status on the date of loss helps route the claim correctly.
| Property situation | Likely policy issue | Question to ask now |
| Owner’s primary home, temporarily empty | Unoccupancy and freezing conditions | What precautions does the policy require while no one is home? |
| Furnished rental with a tenant | Correct landlord coverage and control of heat | Was the rental use disclosed, and who was responsible for heat and inspections? |
| Rental between tenants | Vacancy or unoccupancy restrictions | Did the insurer know the unit was empty, and was heat maintained or plumbing drained? |
| Home under renovation or awaiting sale | Construction or vacancy provisions | Is an endorsement or separate vacant-property policy required? |
A landlord policy may insure the building, owner-owned property, and lost rental income when the applicable loss is covered. It does not ordinarily replace a tenant’s renters insurance for the tenant’s belongings.
Lease obligations, legal fault, and insurance coverage are related but separate questions. A tenant’s possible responsibility for turning off heat does not itself prove that the owner’s property claim is covered or excluded.
“Reasonable Care” Is Built From a Timeline and Records
An adjuster cannot see what happened before the pipe froze unless the owner, tenant, and property manager preserve the evidence. Useful records may include:
- The complete policy, declarations, endorsements, renewal notices, and occupancy disclosures;
- Thermostat settings, smart-sensor alerts, temperature histories, and alarm notifications;
- Utility outage records, fuel-delivery records, and account status;
- Furnace inspection, service, and repair invoices;
- Dated property-check logs, photos, lockbox records, or property-management reports;
- Written winter instructions and communications with tenants, contractors, or caretakers;
- A plumber’s written findings about the break location and apparent cause; and
- Photos and moisture records showing where the released water traveled.
These records do more than show that a pipe broke. They help answer whether the policy was appropriate, whether reasonable precautions were in place, when the heat loss began, and whether the response was prompt.
Protect the Property Without Erasing the Evidence
Coverage investigation should not delay reasonable emergency work. Use this sequence after discovering a frozen or burst pipe:
- Address immediate hazards. Keep away from wet electrical components, sagging ceilings, and unstable flooring. Do not enter an area that appears unsafe.
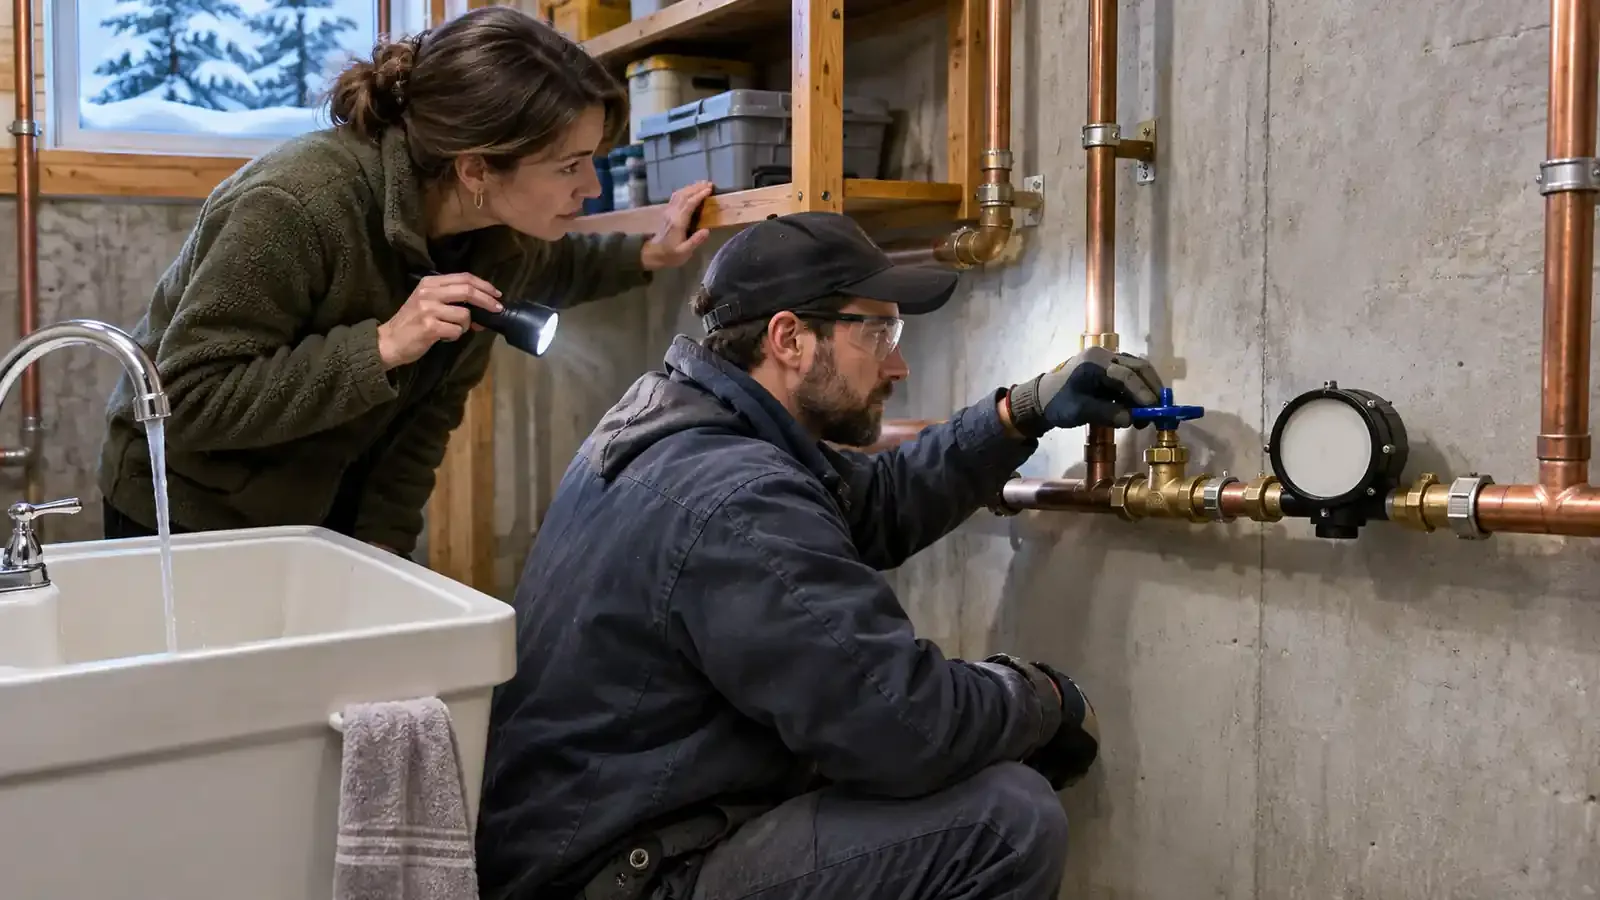
- Stop the water if it is safe to do so. Close the appropriate shutoff or contact the property manager, plumber, or water utility for help. Portland Water advises owners and managers to know the shutoff location and close the main supply when a pipe breaks.
- Notify the insurer or agent promptly. Describe the current facts without guessing about fault. Ask which policy provisions, endorsements, deductibles, and documentation apply. The Washington Office of the Insurance Commissioner advises policyholders to provide requested records promptly and keep copies of claim materials.
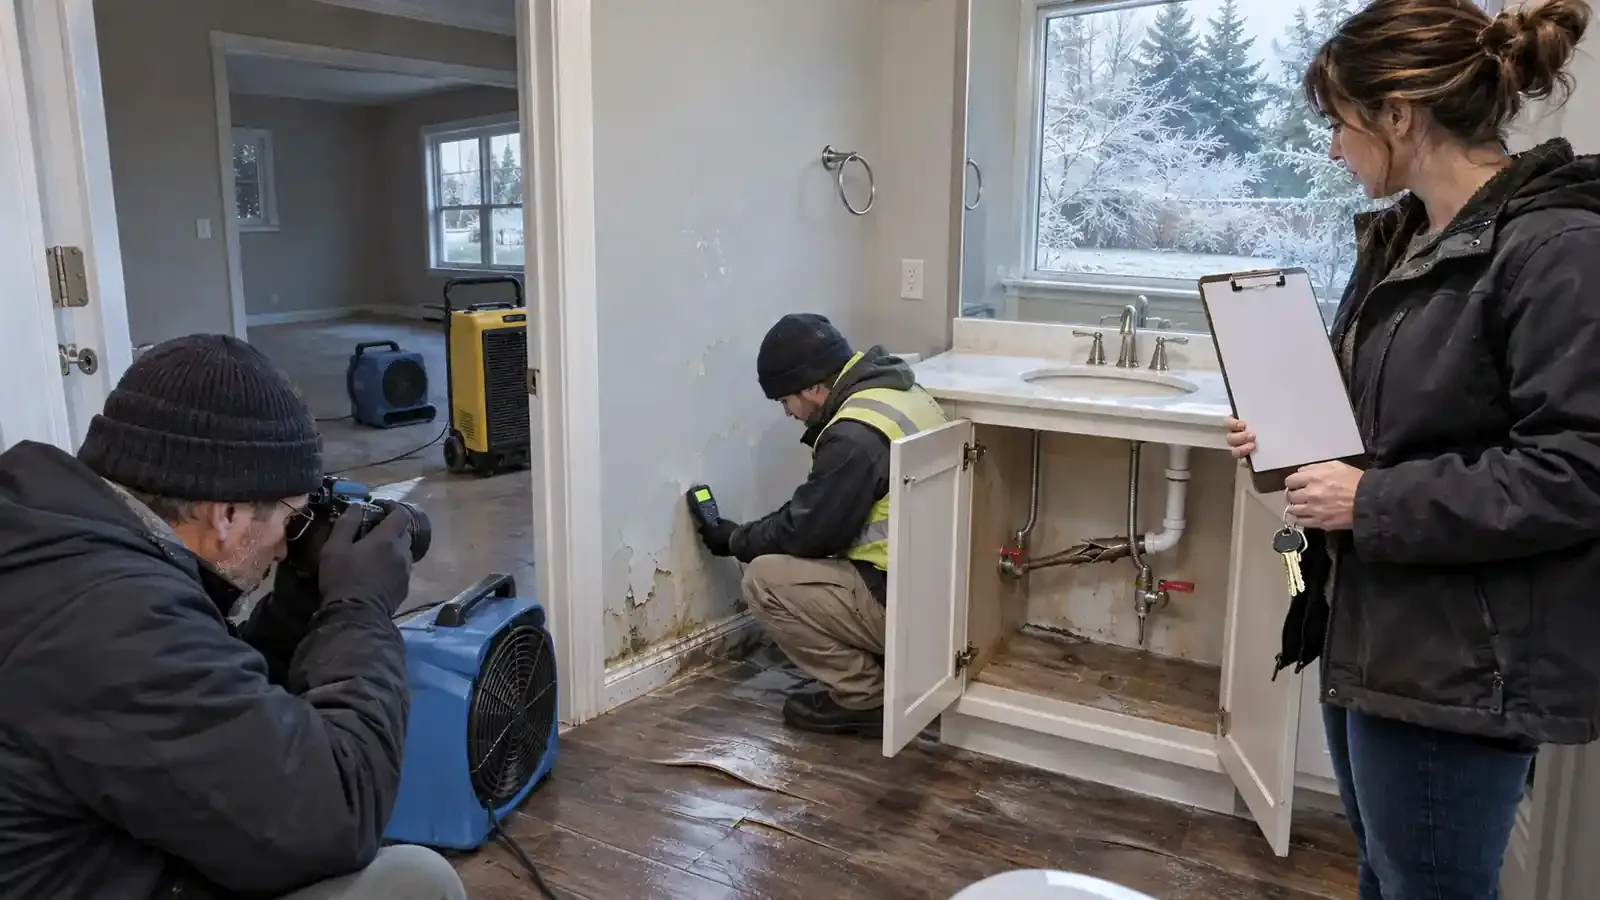
- Photograph before moving or removing items. Record the thermostat, heating equipment, failed pipe area, each wet room, damaged contents, and spaces above, below, and beside the visible leak.
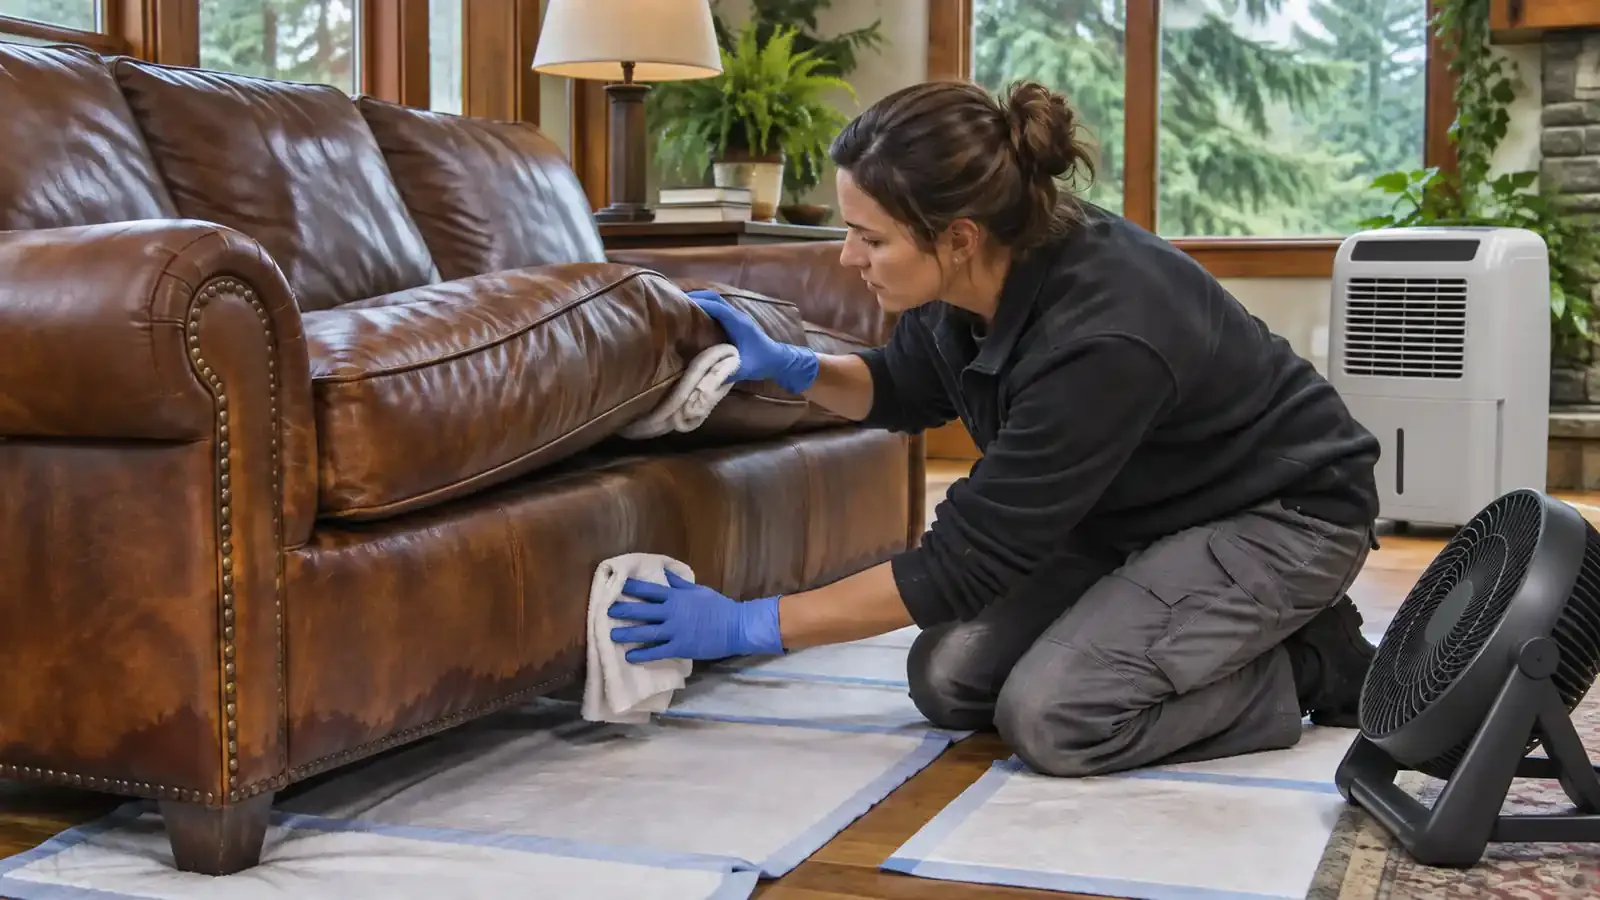
- Arrange source repair and water mitigation. Obtain written plumbing findings and records of extraction, moisture readings, drying, and necessary temporary protection. If water has collected downstairs, basement water removal may be only one part of tracing the full moisture path.
- Preserve receipts and damaged materials when practical. Avoid permanent repairs or discarding evidence until the insurer has had a reasonable opportunity to inspect, unless delay would create a safety issue or allow further damage.
If a frozen-pipe release has affected walls, floors, ceilings, or concealed spaces in the Portland area, our water damage restoration team can assess the moisture path and document mitigation work. The insurer, not the restoration contractor, decides whether the policy covers the loss.
Read the Coverage Decision by Loss Category
A claim decision should identify the relevant policy language and explain how it applies to each requested payment. That makes a partial approval or denial easier to evaluate.
Resulting Building Damage
Sudden water damage to covered walls, ceilings, floors, insulation, and other building materials may be covered when the freezing condition and other policy requirements are satisfied. Long-term leakage, wear, deterioration, or failure to protect the property after discovery can raise separate exclusions.
The Pipe and Heating Equipment
The failed pipe itself may be treated as a maintenance or repair expense even when the resulting water damage is covered. A failed furnace may receive different treatment depending on why it stopped, whether it suffered direct covered damage, and the applicable equipment provisions.
Rent, Belongings, and Temporary Housing
Landlord coverage may include fair rental value when a covered loss makes the unit unfit to rent, subject to limits and time periods. A tenant normally looks to renters insurance for covered belongings and additional living expenses. Neither payment is automatic merely because the unit cannot be occupied; the underlying loss generally must qualify under the applicable policy.
The Practical Answer
Are frozen pipes covered by insurance? They can be, but a vacant or rental property adds two threshold questions: whether the building had the correct policy for its use and whether the insured complied with the freezing provision.
When heat is lost, preserve evidence of the cause, precautions, monitoring, and response. Then ask the adjuster to separate the pipe repair from resulting damage, income loss, owner property, and tenant losses instead of treating the event as one undivided claim.
Frequently Asked Questions
Does homeowners insurance cover frozen pipes in a vacant house?
It may cover resulting water damage if the policy permits the property’s occupancy status and the insured satisfied the freezing conditions. Many policies require reasonable care to maintain heat or to shut off the water and drain the system while the building is vacant or unoccupied. Check the exact definitions and endorsements.
Can a claim be denied if a tenant turned off the heat?
Possibly. The insurer may examine the landlord policy, the tenant’s actions, who controlled the utilities, written instructions, property monitoring, and the freezing exclusion. A tenant’s conduct may also create a separate liability or lease dispute, but it does not determine coverage by itself.
What if a power outage or furnace failure caused the heat loss?
An unexpected outage or mechanical failure can support an argument that the loss was not caused by intentionally leaving the property unheated. Coverage still depends on the policy and whether the owner responded reasonably to warnings, maintained the system, monitored the property, or drained the plumbing when conditions required it.
Are “vacant” and “unoccupied” the same in an insurance policy?
Not necessarily. A policy may define them differently, and restrictions may attach after different periods or under different conditions. A furnished home whose occupants are temporarily away may be treated differently from an empty building awaiting sale or a unit between tenants.
Does home insurance cover the broken pipe itself?
Often, the resulting sudden water damage is treated more favorably than the cost to repair the failed pipe. Access, tear-out, plumbing repair, and reconstruction can also be handled differently. Ask the adjuster to identify the policy provision for each category.
Can landlord insurance pay lost rent after a frozen pipe?
It may provide fair-rental-value coverage if a covered loss makes the rental unfit for use. Limits, waiting periods, the expected repair period, and the property’s actual rental status may affect payment.
Does the owner’s policy cover a tenant’s damaged belongings?
Usually not. The owner’s property policy generally addresses the building and insured owner property. A tenant typically needs renters insurance for covered personal property and additional living expenses.
Should an owner shut off and drain the water whenever a property is empty?
Follow the policy, insurer instructions, plumbing design, and qualified winterization guidance. Shutting off and draining may satisfy one common freezing condition, but fire-sprinkler systems, boilers, appliances, irrigation, and other equipment can require specialized procedures. Do not disable a protected system without appropriate authorization and professional guidance.